01
Lender charges
The lender's fees for setting up and processing the loan. I make sure you know where these sit in the estimate.
Maryland · DC · Virginia
VA home buying across the DMV
The real number at the closing table is knowable. And part of it may be negotiable.
Just a conversation. No paperwork, no pressure.
For veterans and military families buying across Maryland, Washington DC, and Northern Virginia.
The number nobody names
I meet veterans who know the VA loan can offer zero down. What no one has shown them is the cash-to-close estimate that includes everything else. I work that specific number before you decide what is possible.
Local context: Prince George's County was around a $450,000 median sale price in April 2026, down roughly 1% year over year. Active listings were up close to 30%, with more months of supply than any other Maryland county in the metro. Median gross rent was around $1,799 monthly, roughly 23% above the Maryland average. All figures are approximate and change.
What you actually bring
The lender's fees for setting up and processing the loan. I make sure you know where these sit in the estimate.
Title work, settlement services, and transfer and recordation taxes. This part changes when you cross a state or district line.
The appraisal, insurance, property tax reserves, and prepaid interest can all add to the number due at settlement.
This fee may apply and can often be financed. A lender can confirm the amount and whether an exemption is documented.
Maryland, DC, and Virginia each handle transfer taxes differently. The same purchase price can produce a different closing number depending on which side of the line you buy on.
Who else can pay
A seller can agree to pay certain closing costs. That contribution is negotiated as part of the offer. It is never guaranteed, but it is one of the tools I consider when the numbers support it.
Maryland has offered veteran and military programs that may include a rate discount, down payment and closing cost assistance, partner match funds, and a mortgage interest tax credit. Some programs have made exceptions to first-time buyer rules for veterans. Programs, amounts, and terms change. A lender can confirm current options and eligibility.
Nationally, only an estimated 10% to 15% of eligible veterans have ever used a VA loan benefit. That figure is approximate and changes. The only useful question is what your own documentation and numbers show.
Complimentary. Confidential. No obligation.
What happened at settlement
01
Two first time veteran buyers had their full closing costs covered by the seller. Because those credits covered what they owed at the table, their earnest money deposits came back to them at settlement.
02
A military family coming off a long PCS bought on their terms after repeated pushback from the seller, closing with a price reduction and four percent of the purchase price in seller paid closing costs.
Past results. Seller contributions are negotiated and vary by transaction.
Who I work with
01
You have held your VA benefit for years, but renting still felt simpler than figuring out the process.
02
You are around Andrews, Meade, Pax River, Indian Head, Bolling, Belvoir, or the Pentagon and you are tired of renewing.
03
You are separating or retiring and deciding whether Maryland, DC, or Northern Virginia is where your family puts down roots.
04
A call center lender said no once. I can connect you with a lender who will review the actual documentation and explain the next step.
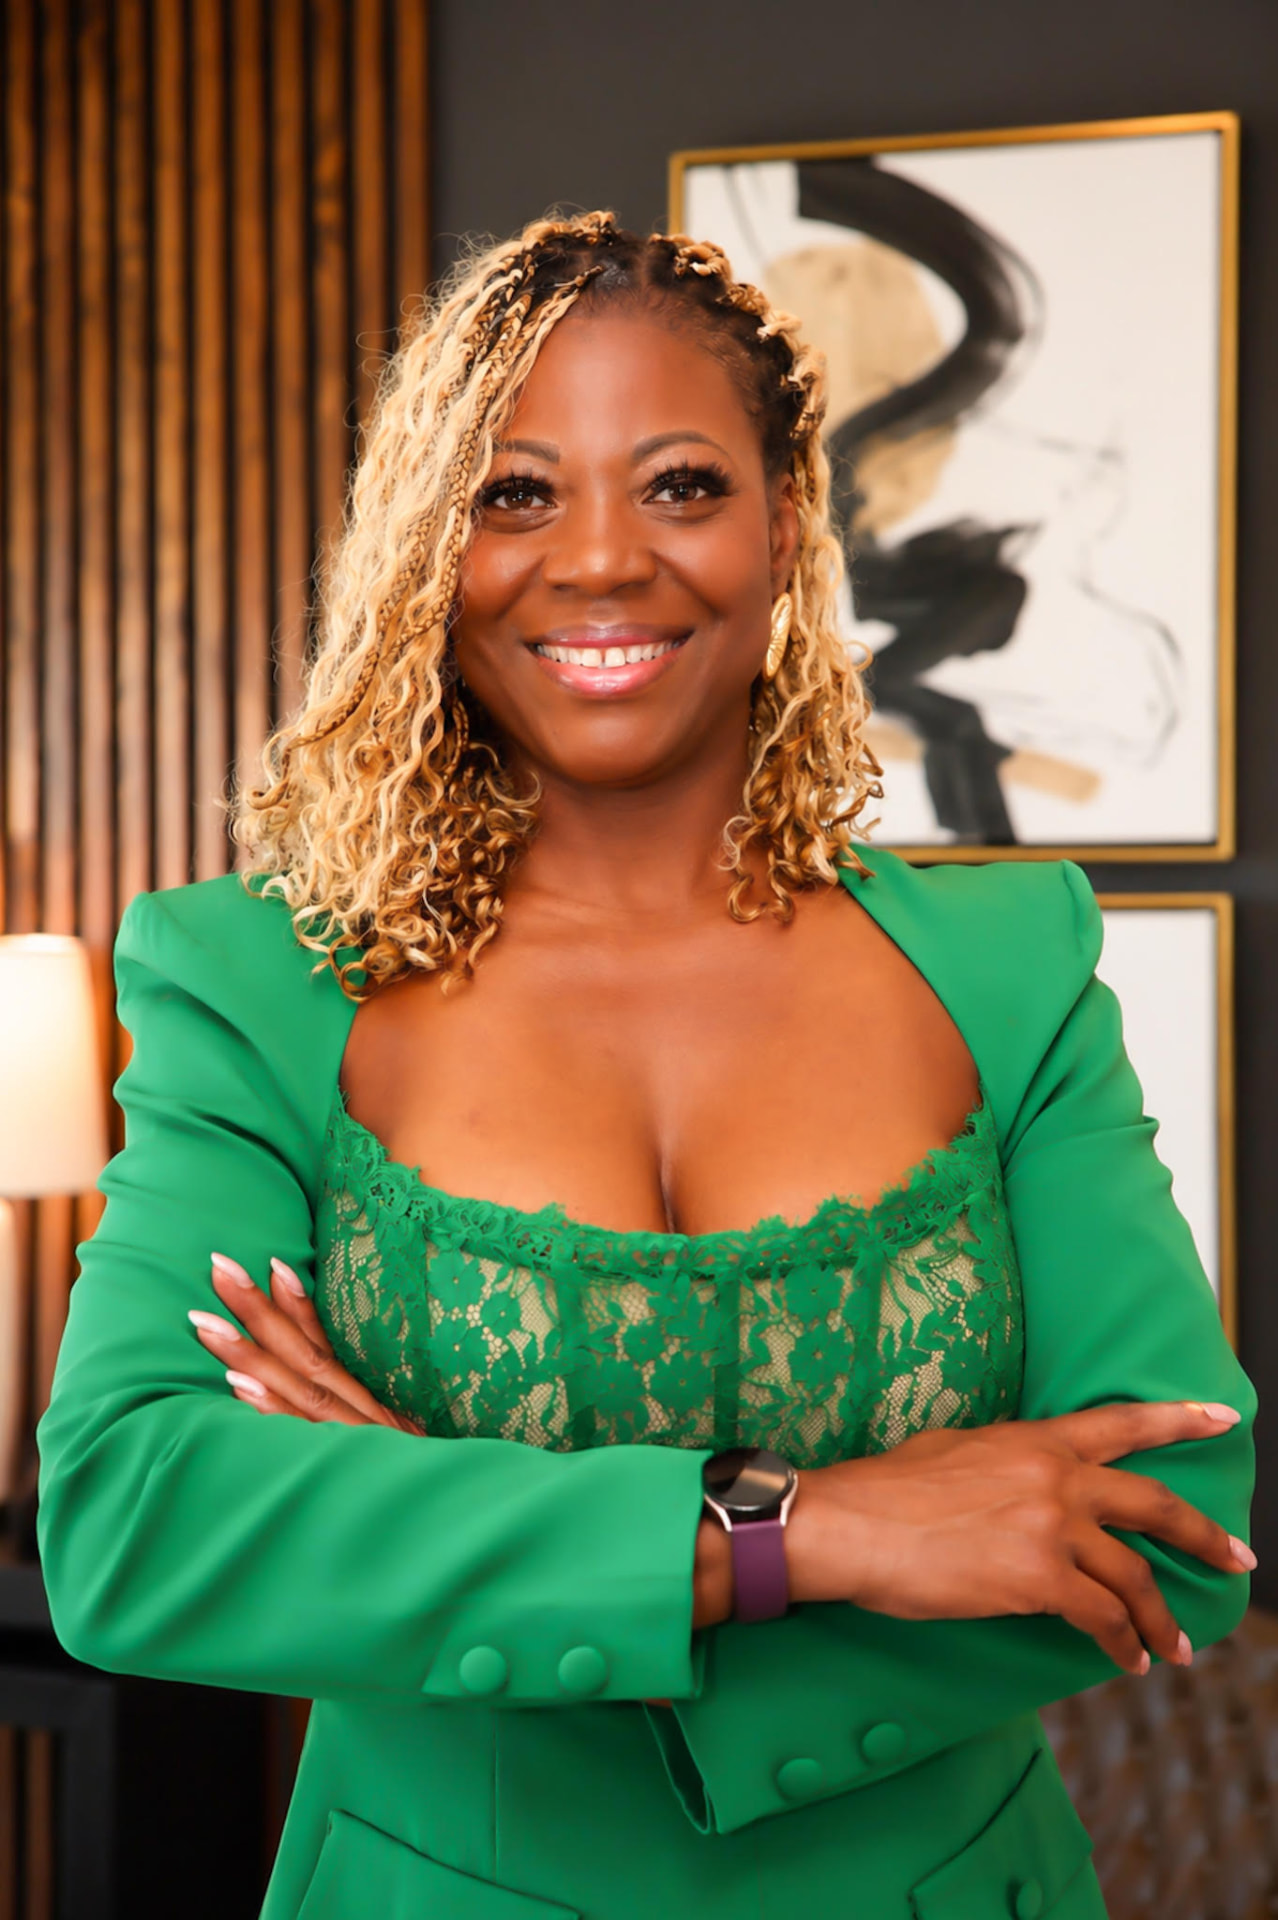
About Rhonda
I recently retired from the US Army after 33 years of service. Today, I help veterans and military families move toward homeownership across Maryland, Washington DC, and Virginia without feeling overwhelmed by the process.
I know a move can be driven by orders, a lease ending, separation, or retirement. I also know that crossing from Prince George's County into DC or Northern Virginia changes the transaction. I stay focused on the numbers, the timeline, and the solution in front of us.
I have been recognized by my brokerage every year since 2020, including a year leading my team in contracts and units closed.
Common worries
I start with the number, not a house search. Once we know the real cash-to-close range, we can see whether a path makes sense.
You do not need to arrive prepared. I will lay out the order of operations and connect you with a lender who can confirm the financing details.
Neither should be guessed at. A lender can review the full picture, and if work is needed, we can identify a practical next step.
That is exactly why we separate down payment from cash to close. Then we look at negotiated seller credits and programs worth asking a lender about.
One useful conversation
I will help you see what the closing table could actually require, then you can decide what makes sense for your family.
Fifteen minutes. Nothing to sign.